- Japan’s policy rate has reached 1.25 per cent, its highest level in 31 years.
- The BOJ is increasingly focused on preventing inflation from moving above its 2 per cent target.
- The weak yen, higher energy costs and pressure on borrowing costs could complicate the next phase of rate hikes.
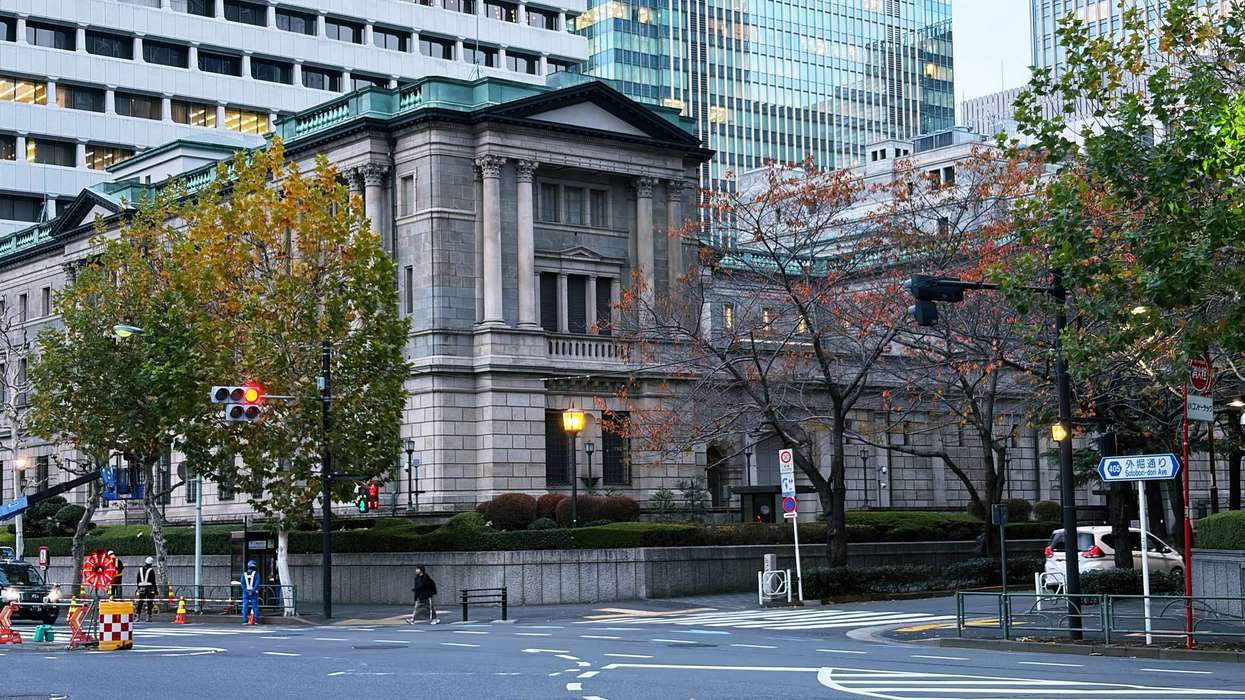
The Bank of Japan (BOJ) raised its policy rate by 25 basis points to 1.25 per cent on Friday (18), taking it to its highest level since 1995. The seven-to-two decision was widely expected, but the speed of the move shows that the central bank is becoming less willing to wait for inflation pressures to build further.
The latest increase came only three months after the previous one, making it the shortest gap between rate increases during governor Kazuo Ueda’s tenure. Board members Toichiro Asada and Ayano Sato opposed the move, arguing that economic and price conditions did not yet justify another increase.
For years, Japan was an outlier among major economies, keeping interest rates at or below zero in an effort to encourage borrowing, spending and investment and escape a prolonged period of deflation. The latest hike is another step in the BOJ’s attempt to normalise monetary policy after that long experiment with ultra-low rates.
The immediate concern is inflation. The BOJ wants underlying inflation to remain around its 2 per cent target, rather than allowing higher prices to become entrenched and eventually hurt households and the wider economy. Governor Kazuo Ueda said the bank needs to ensure underlying inflation does not move significantly above 2 per cent.
Japan’s headline inflation rate was 1.9 per cent in August, while core inflation stood at 1.7 per cent, according to the figures cited ahead of the decision. That gives the BOJ some room to move cautiously, but rising energy costs and a weak yen remain concerns because Japan relies heavily on imports.
The yen problem
Higher interest rates would normally be expected to make a currency more attractive by improving returns on assets denominated in it. Yet the yen weakened after Friday’s decision, with investors focusing on the two dissenting votes and the absence of a firm signal about when the next hike could come.
That creates a difficult balancing act for the BOJ. A weaker yen makes imported goods and energy more expensive, potentially adding to inflation. But raising rates too quickly could increase borrowing costs for businesses and households and put additional pressure on an economy that is still recovering.
The issue is particularly important for small and medium-sized businesses, which can be more sensitive to higher financing costs. Mortgage borrowers could also face higher costs as rates move further away from the exceptionally low levels Japan has maintained for years.
The yen’s weakness has also attracted attention from Washington. US Treasury Secretary Scott Bessent has urged Japan to take steps to address currency volatility, while US-Japan authorities have recently intervened in foreign-exchange markets to support the yen.
At the same time, Japan’s government under Prime Minister Sanae Takaichi has backed expansionary fiscal policies, including increased spending and investment. That creates another tension for monetary policymakers because stronger government spending can add to demand and potentially make inflation harder to contain.
The BOJ is therefore trying to navigate between several competing risks rather than simply chasing a higher interest rate. It wants inflation close to 2 per cent, a more stable yen and a gradual return to more conventional monetary policy without damaging economic growth.
Ueda has stressed that the bank does not have a fixed timetable for future increases. He said it would assess whether its economic and inflation forecasts are being realised before deciding how quickly to move next.
For Japan, the significance of Friday’s decision is therefore not just the 1.25 per cent figure. It marks another step in a much bigger shift away from the monetary policies that defined the country’s economy for decades.
The question now is how far that normalisation can go without creating a new problem for the economy it is designed to protect.